


Decided to post some ramblings on Anthropic, AI, & Neoclouds since everyone else is jumping in. A few highlights:
AI economics, across the entire chain, are stronger than we thought
Anthropic & Frontier Labs still have enterprise adoption runway
Margins are high enough to subsidize training & R&D
Neoclouds are in a stronger spot than the market suggests?
h/t @The_Analyst_Lab, @GavinSBaker, @alexsongis and SemiAnalysis
This thread is for informational purposes only and is not investment advice; figures come from public filings, third-party data and our own estimates, and may be inaccurate, incomplete or out of date.
Healthy Demand for Compute
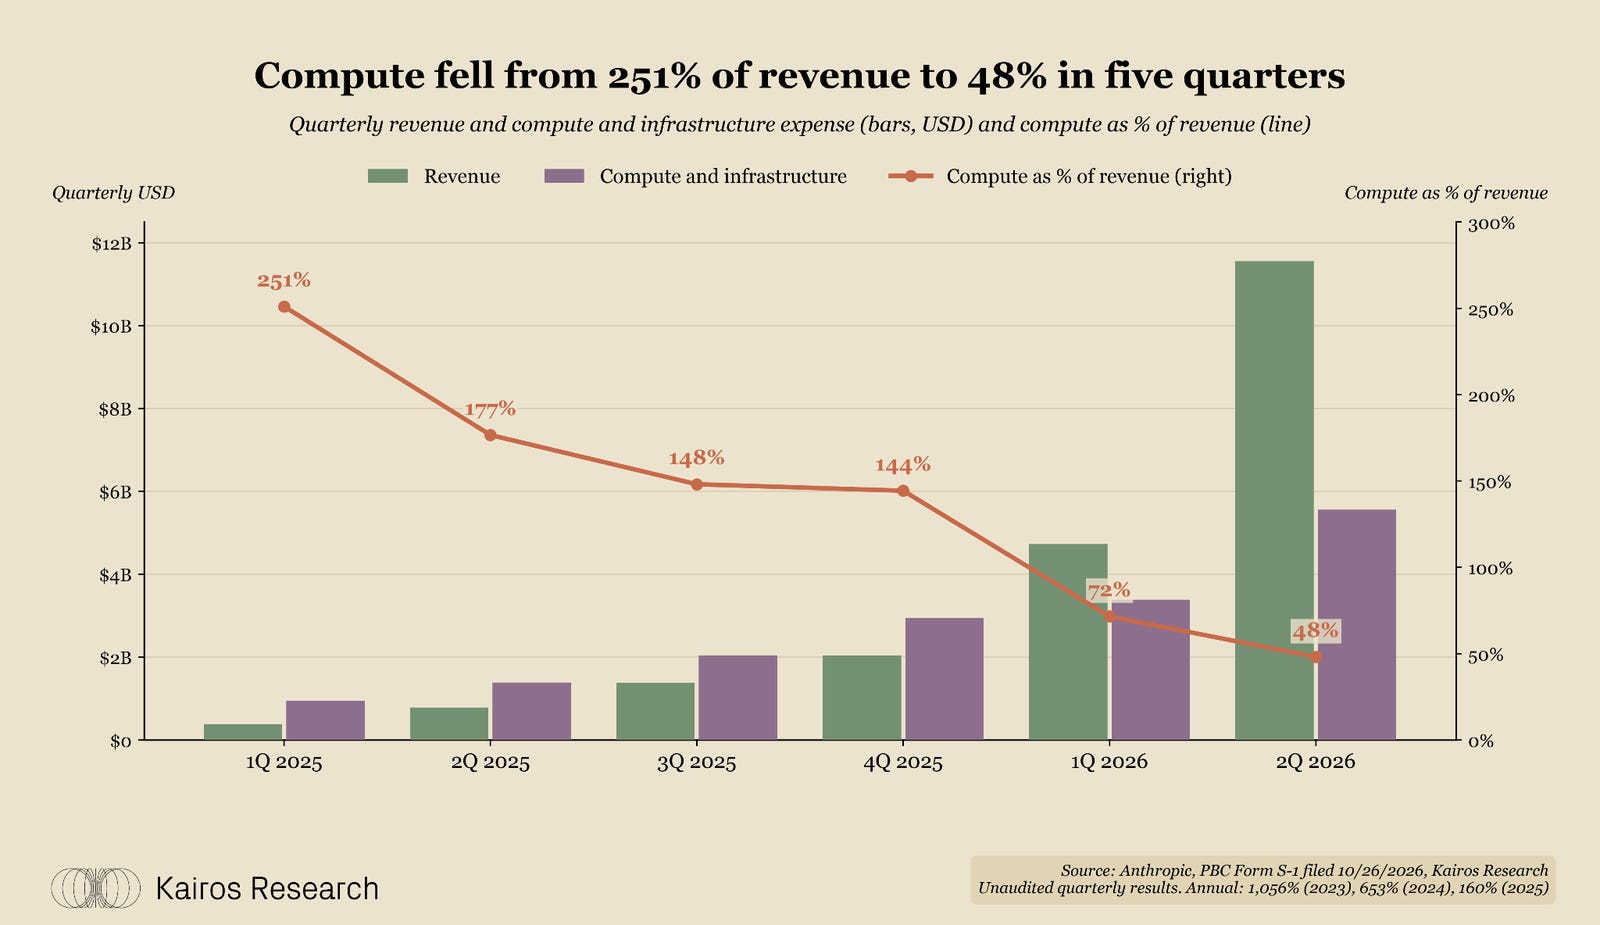
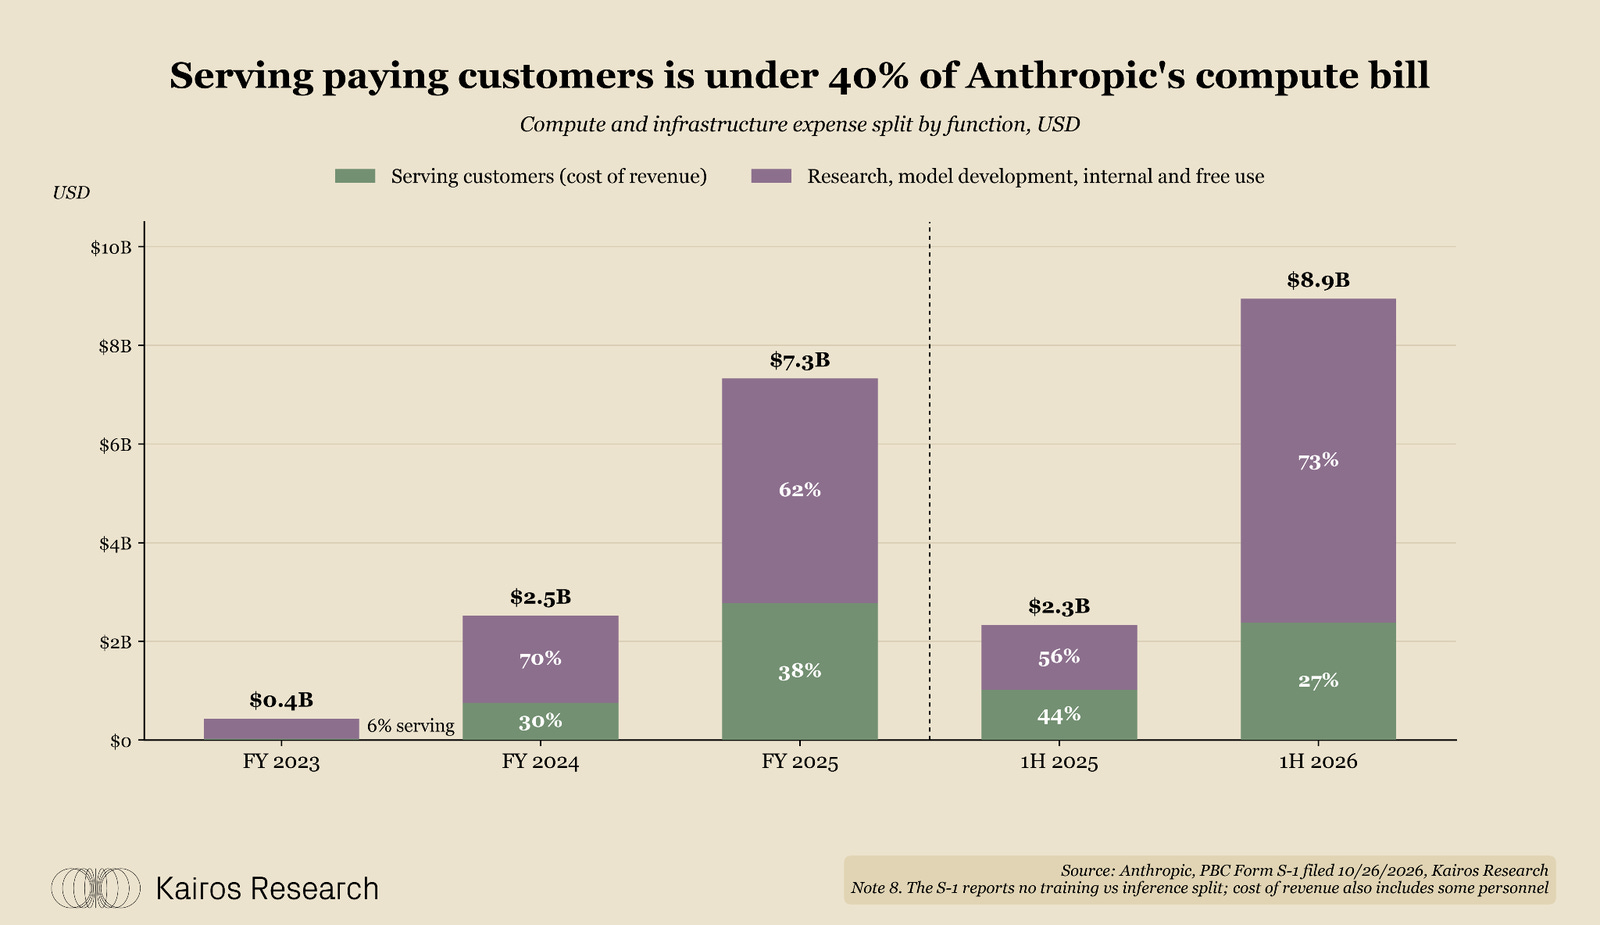
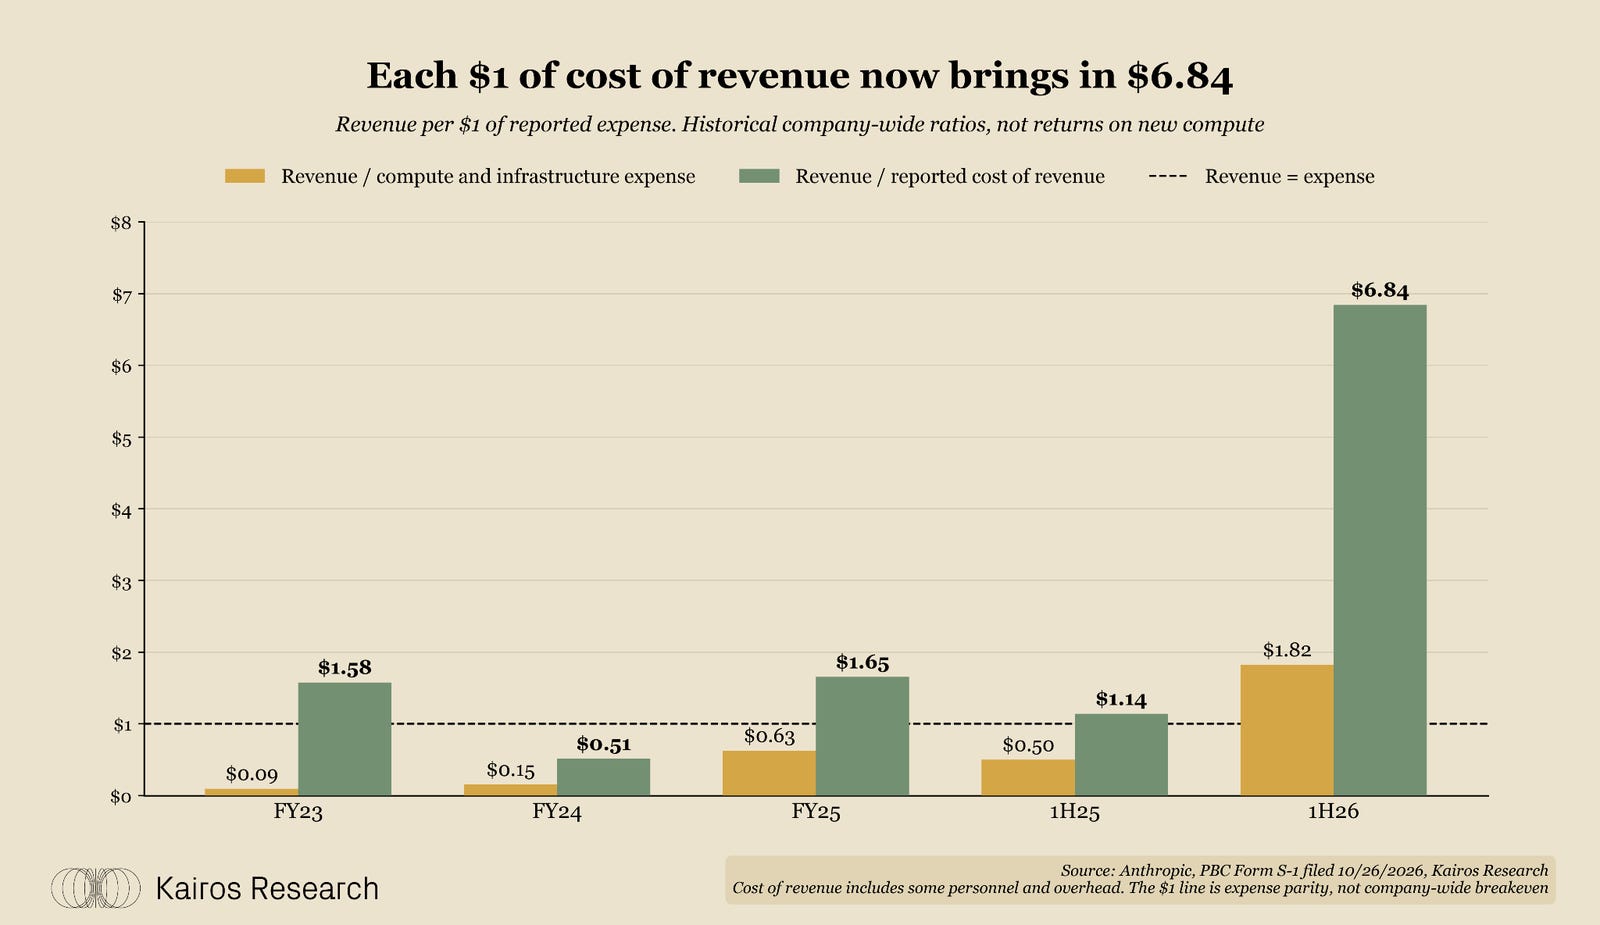
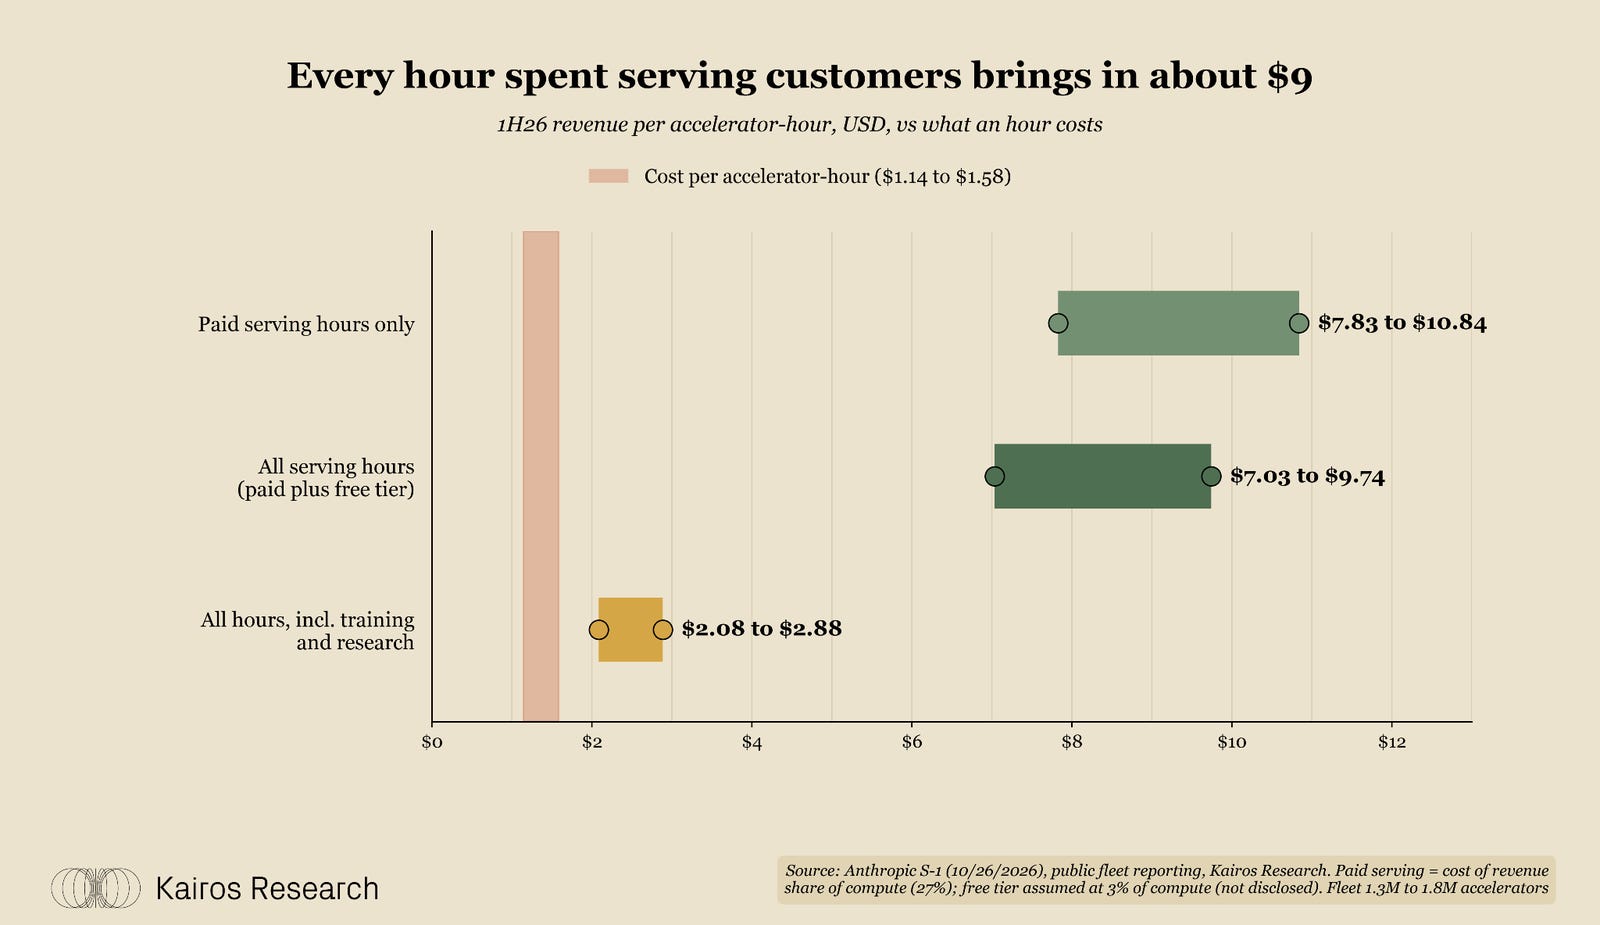
Compute and infrastructure fell from 251% of revenue in Q1 ‘25 to 48% in Q2 ‘26, while the dollar spend (especially on training) increased. Only ~27% of H1 ‘26 compute shows up in cost of revenue, a rough proxy for serving paying customers. The rest funds research, model development, internal use and free tiers.
Paid usage is now covering a growing share of the research bill. Our takeaway is that popular models are getting increasingly efficient and competition between the Labs will become an increasingly important piece of neocloud demand in the future.
Significant Enterprise Runway
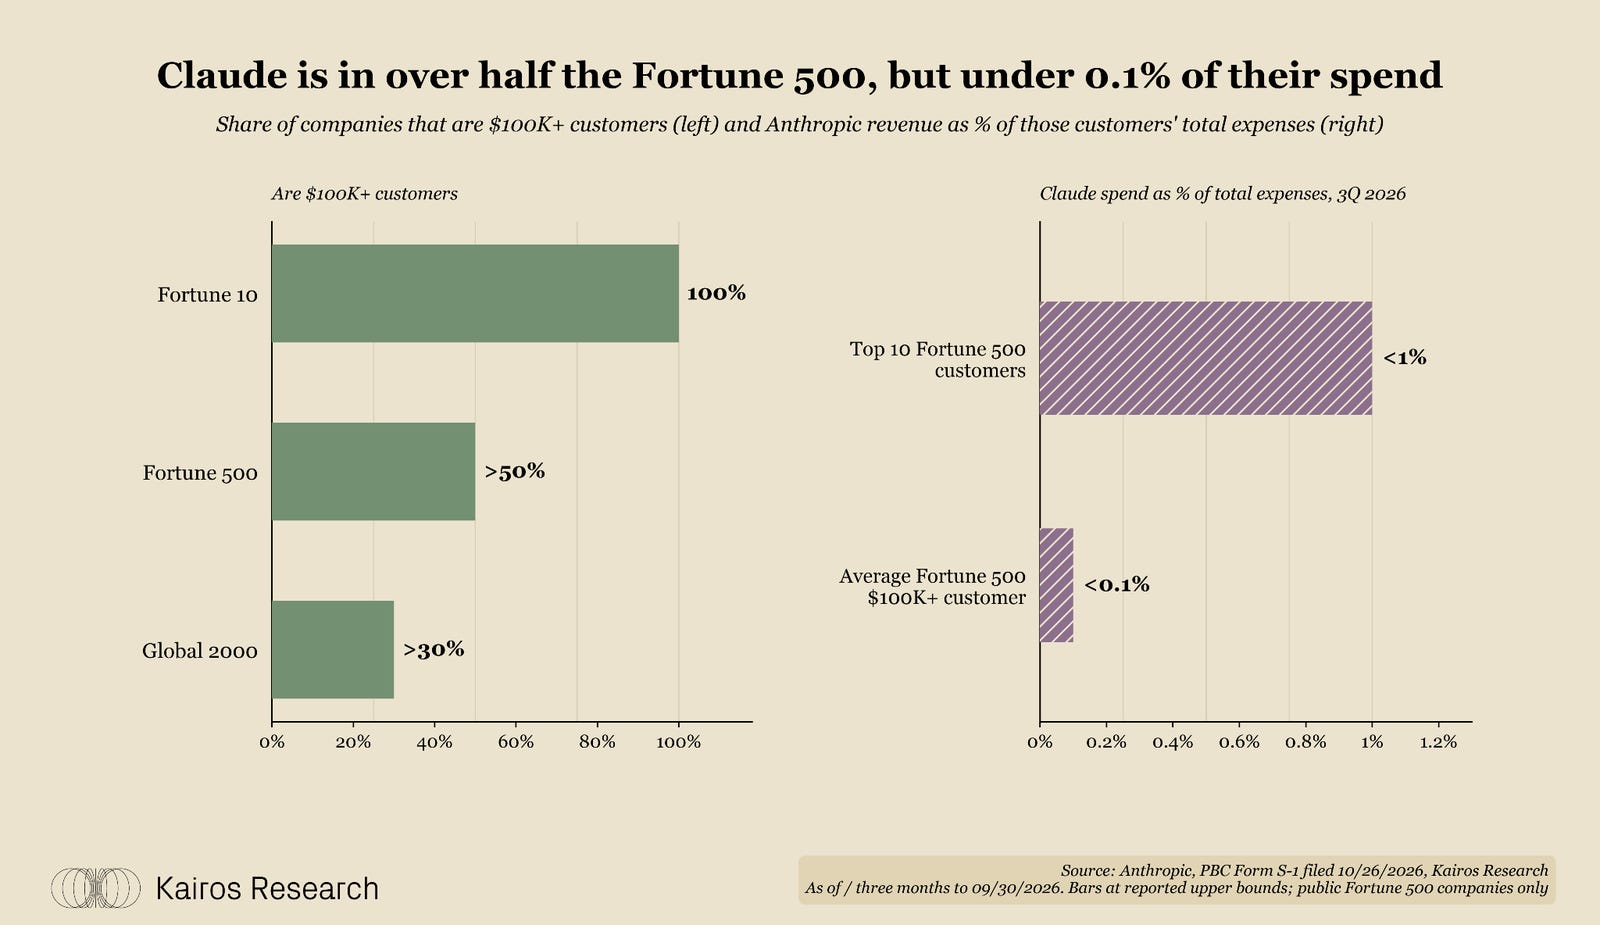
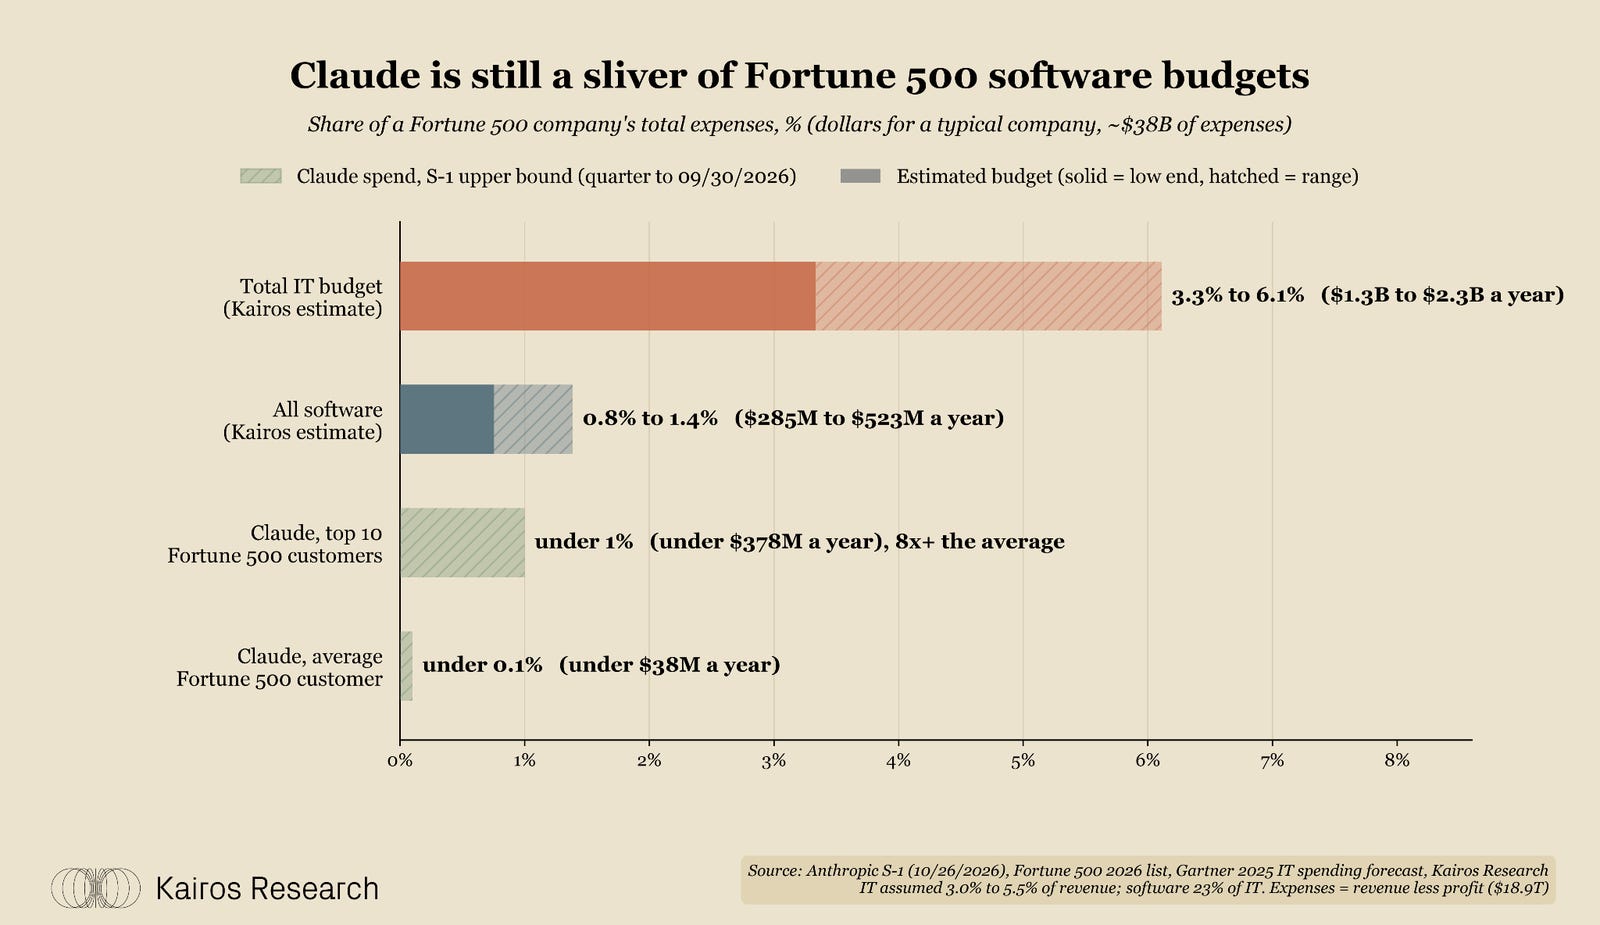
Over half the Fortune 500 now pay Anthropic $100K+ a year. But on average, Claude is under 0.1% of total expenses. Even the top 10 spenders remain under 1%.
For scale, a typical Fortune 500 company spends an estimated $285M to $523M a year on software alone. Average Claude spend could grow 8x and still sit inside that budget, before touching labor or services spend. Anthropic clearly has to continue delivering a superior product to justify these margins down the road.
Smart Models Get Strong Margins
Anthropic made $6.84 of revenue for every $1 of reported cost of revenue in H1 ‘26, up from $1.14 a year earlier. That’s roughly an 85% gross margin, before R&D, sales, and G&A.
For an outside reference, DeepSeek reports $38 of revenue per GPU-hour on one V4.1 Flash serving cluster at off-peak pricing. We remain skeptical about the stickiness of this number.
It fits @GavinSBaker‘s view that value can & has accrued across the supply chain.
Fixed vs Spot Compute Costs
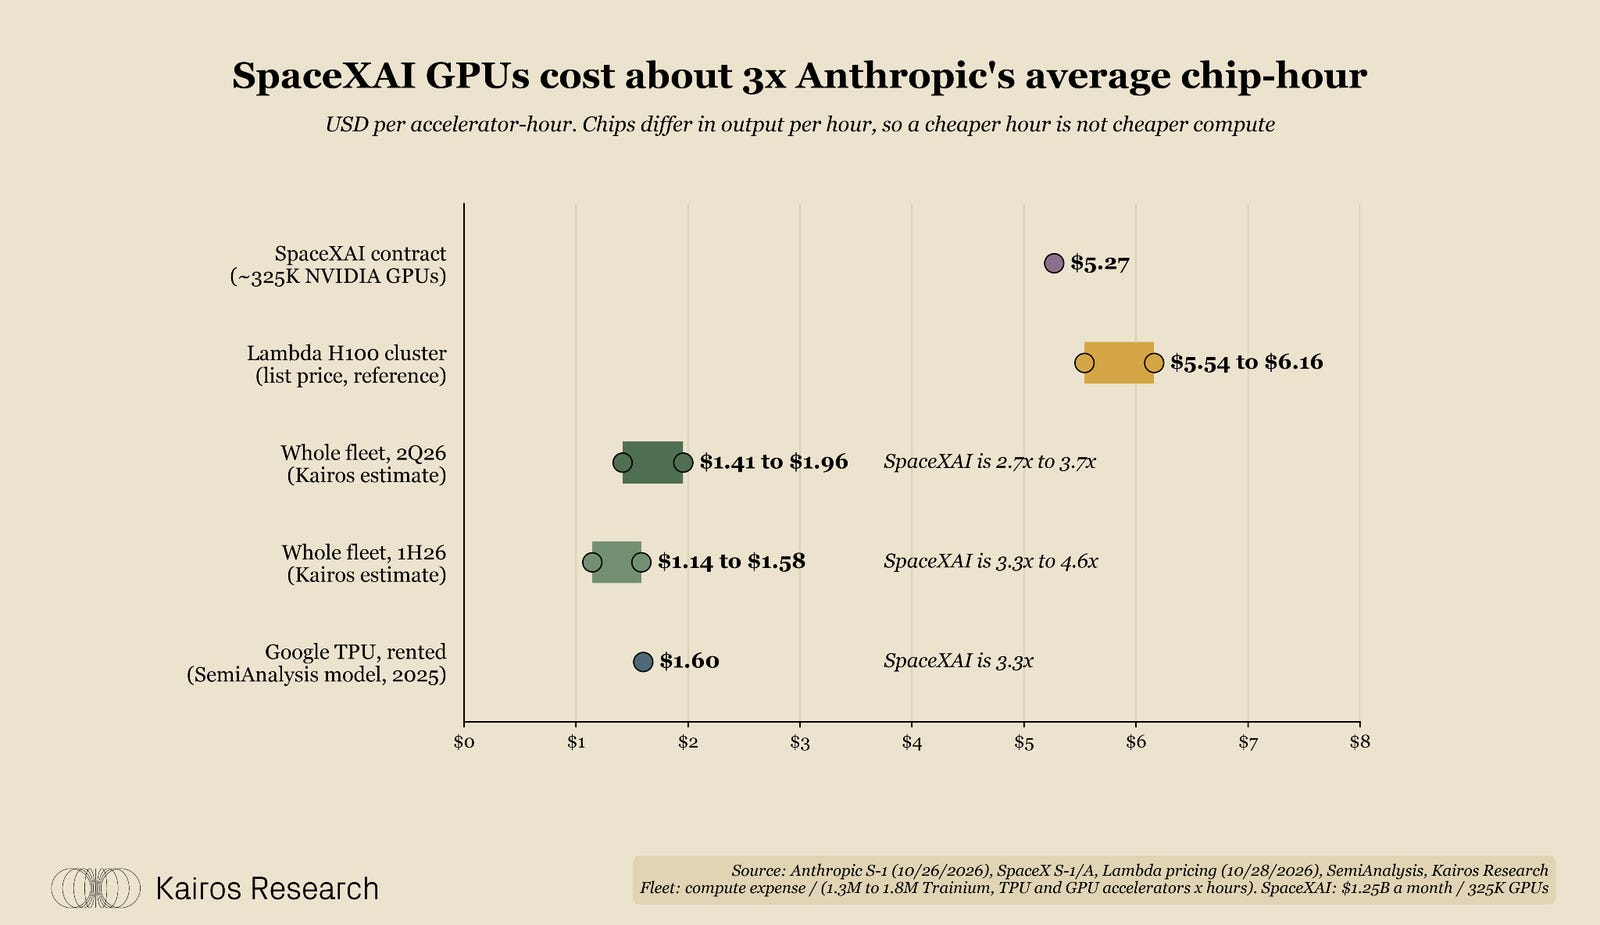
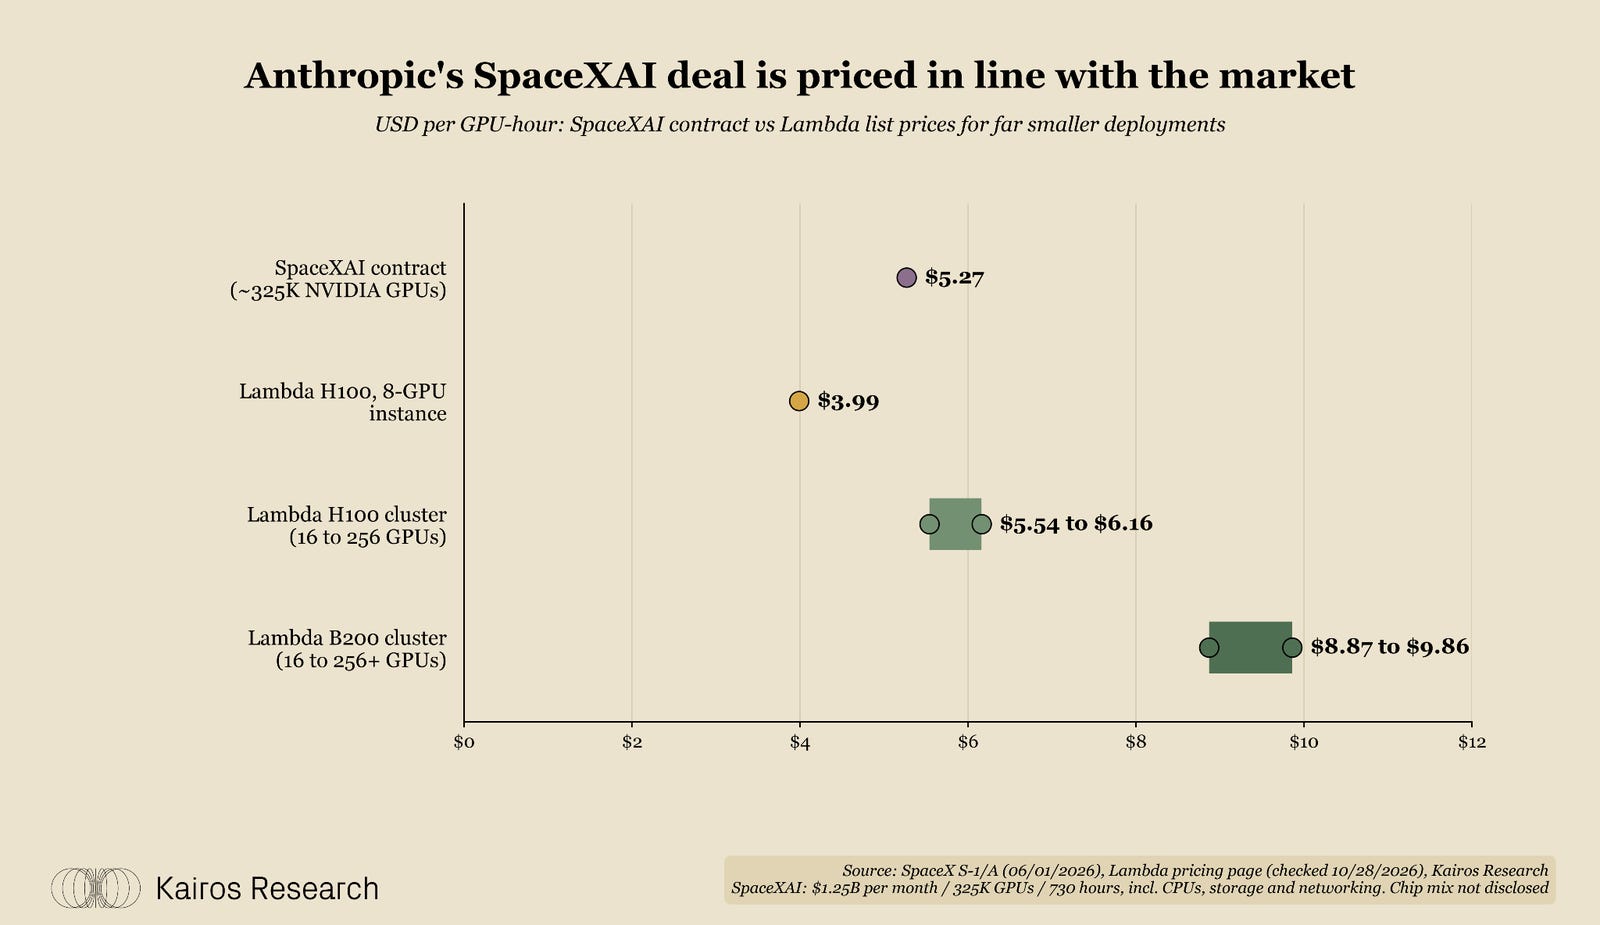
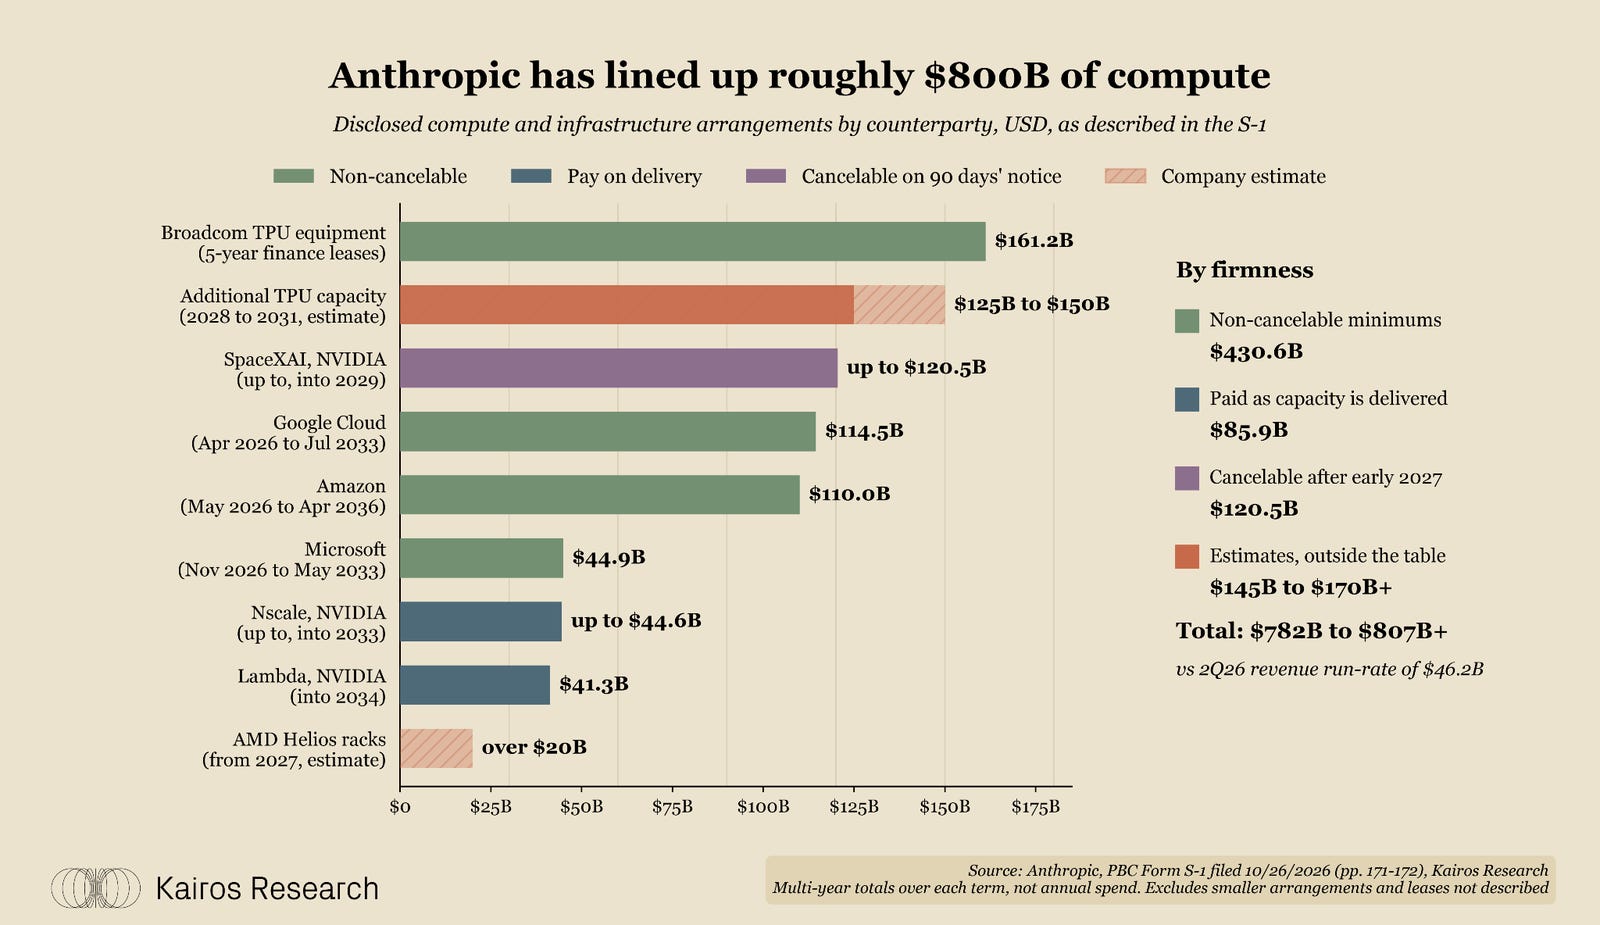
Anthropic’s original SpaceXAI deal was $1.25B a month for ~325,000 NVIDIA GPUs. That’s about $5.27 per reserved GPU-hour. That’s more in line with Lambda’s current spot GPU pricing than it is with Anthropic’s other long-term contracts. The deal has since grown to ~$3.1B a month at full capacity (Dec ‘26), cancellable on 90 days’ notice after early 2027.
We also saw Google announce yesterday that they dipped into third party compute at the end of Q3 and will ramp that up in Q4, suggesting available demand at neoclouds will continue to be extremely valuable.
The Neocloud Problem
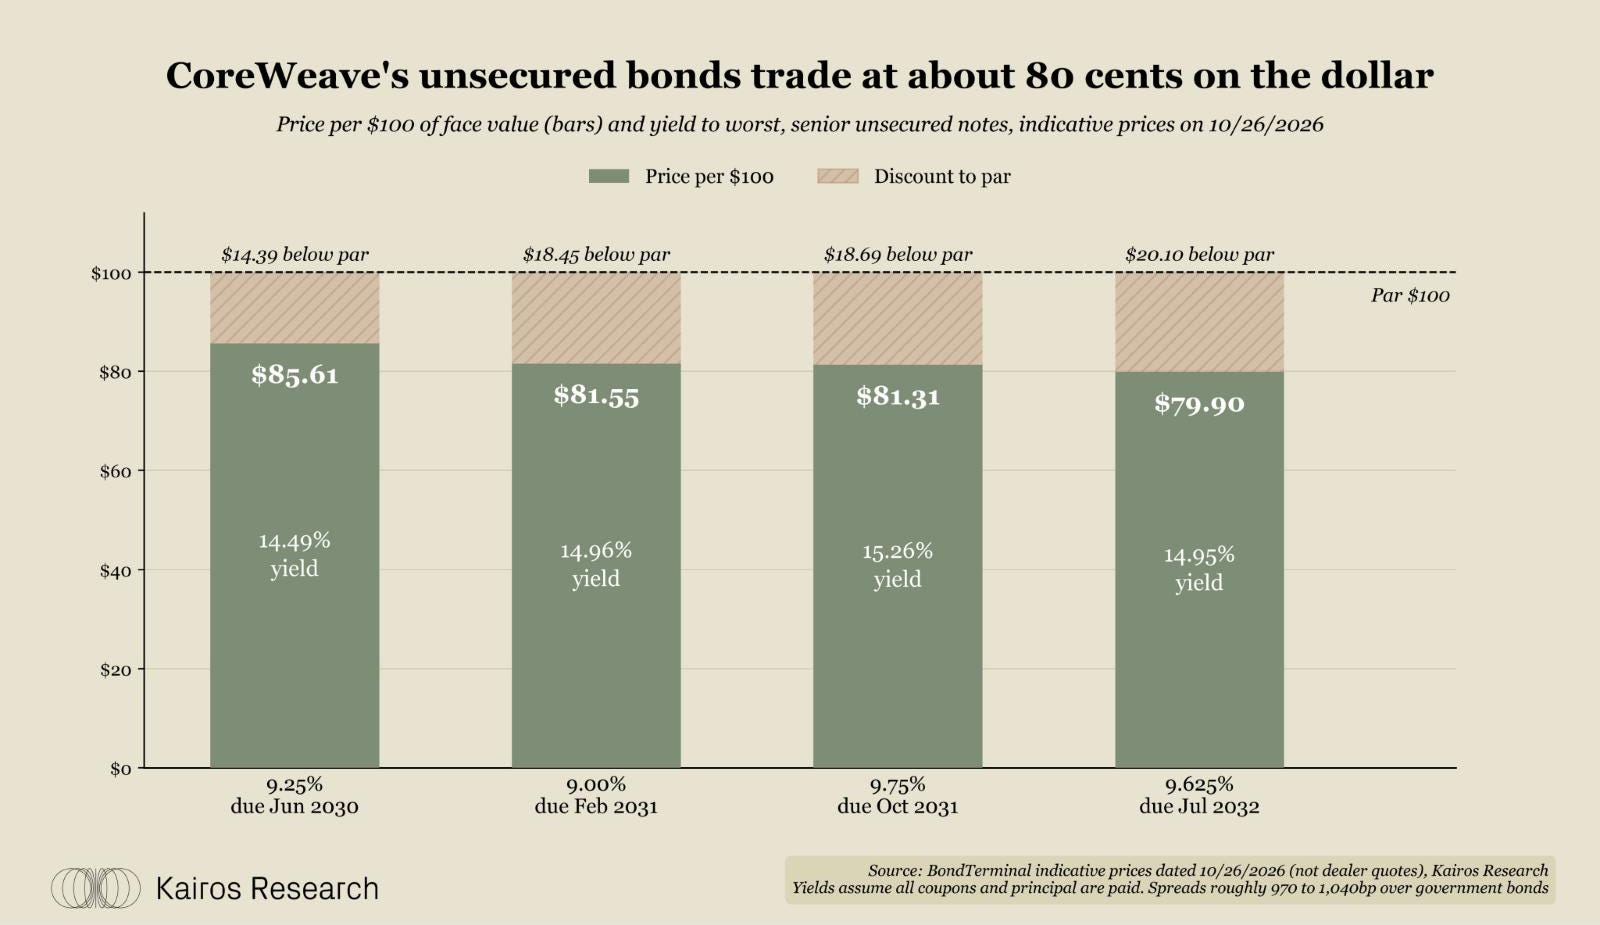
We thought Anthropic’s S-1 & Google’s earnings presented a bull case for compute demand / neoclouds. The market seems to disagree, with SPCX, NBIS, CRWV, & IREN all trading down since then. Coreweave’s unsecured notes trade at $80 to $86, yielding ~15%.
There is obviously a lot more nuance to the situation, given some neoclouds have spot capacity and others have signed long term contracts way below market price. There are also clearly issues with getting data centers stood up & online.
We believe that the recent data (spot GPU pricing, demand for AI, training spend) suggests that demand should not be a problem at all for Coreweave & elevated spot prices can clearly reward their ability to get compute online ahead of schedule – the CEO mentioned that recent short term deals are delivering contribution margins ~10% higher than contracts signed in previous quarters.
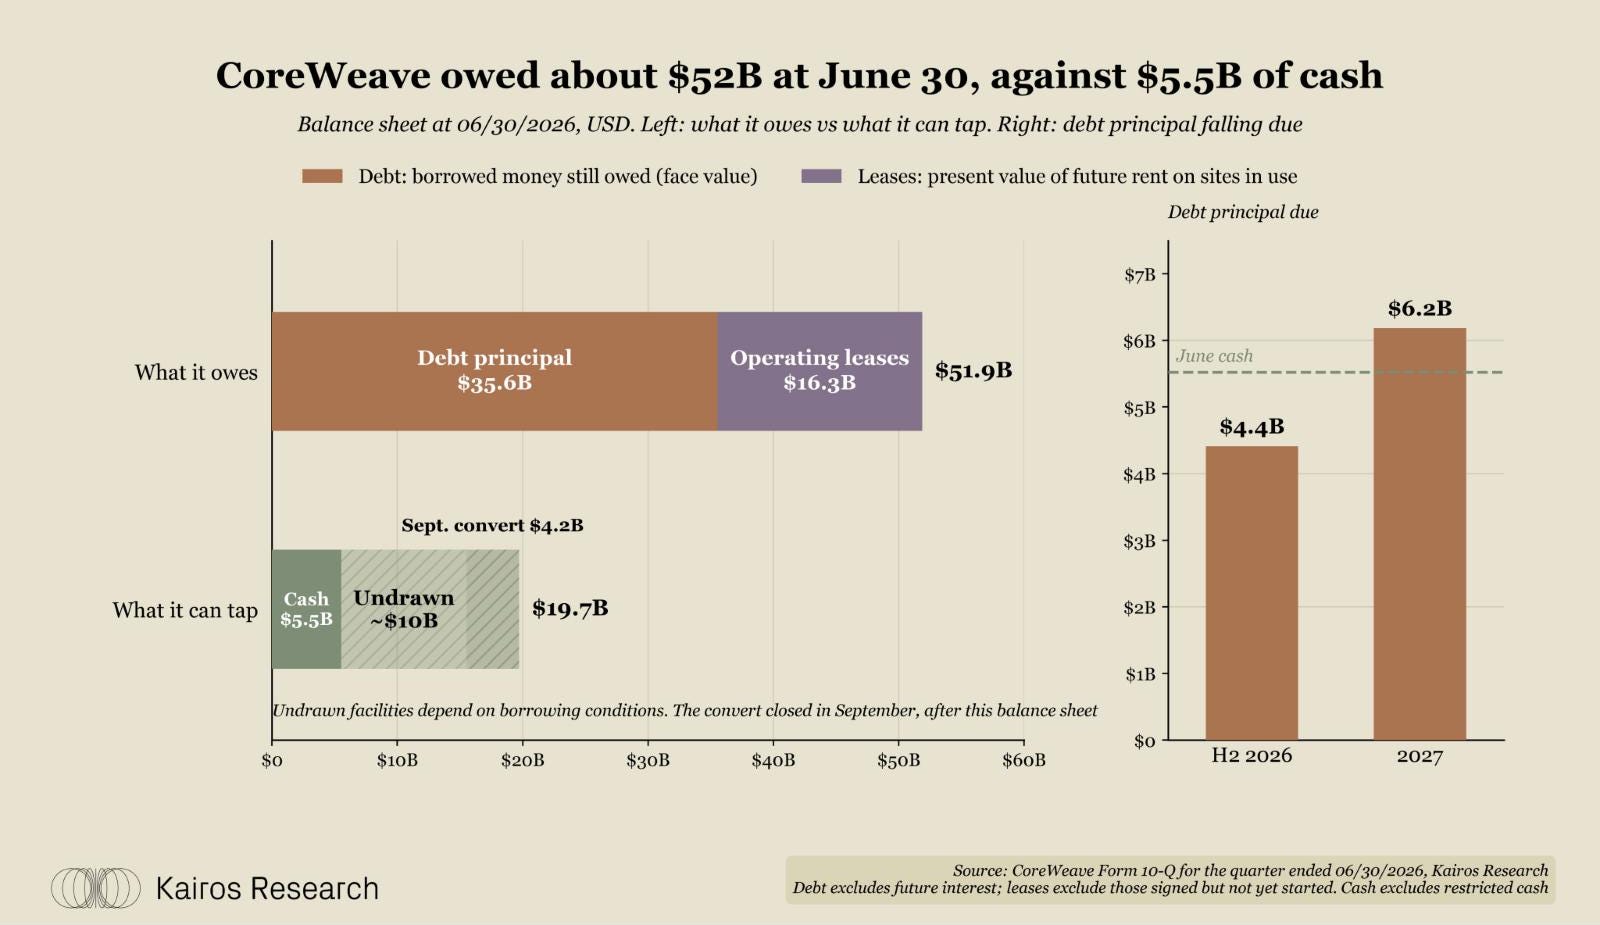
Given the bonds are unsecured, the largest concerns would be the company’s ability to get supply online on time / financing the gap if there are any delays.
Backup: CoreWeave in numbers
Latest reported statements cover June 30, 2026. Q3 results are due November 10. Figures are consolidated.
Why the bonds yield 15%
Priority. The best collateral sits in project vehicles. DDTL 4.0 is an $8.5B investment-grade facility secured by infrastructure and a customer contract. The unsecureds are junior to this in the cap stack. S&P rates them B with a 10% to 30% recovery band in its default scenario.
Term mismatch. The August $2.6B facility runs five years against contracts averaging three. Renewals have to fund the tail.
Concentration. Three customers were 72% of Q2 revenue. About 98% is committed take-or pay, which helps, but only if capacity is delivered and customers pay. We believe the underlying asset & customer credits are both good.
Timing. Active power was 1.5GW at Q2 against 4.2GW contracted in August. Any delays postpone revenue while interest responsibilities add up. Coreweave’s contracts are mostly priced under current market prices, making neoclouds with available capacity more interesting to the market.
Sources
Checked October 28, 2026. Writing is Kairos Research analysis.
Anthropic S-1, October 26, 2026. Quarterly figures pp. 158-159; Fortune 500 pp. 142-143; cost of revenue Note 8, F-40; SpaceXAI p. 172
SpaceX S-1/A, June 1, 2026. Compute Services Agreements, p. 14: ~325,000 GPUs, $1.25B per month
Anthropic, SpaceX compute deal, May 6, 2026. Higher usage limits tied to new capacity
Lambda GPU cloud pricing. H100 and B200 instance and cluster list prices, checked October 28, 2026
DeepSeek V4.1 Flash deployment Q&A. $38 per GPU-hour, one cluster, off-peak pricing
Gavin Baker, a16z interview, August 31, 2026. Value across the AI supply chain
SemiAnalysis, TPUv7: Google Takes a Swing at the King, Nov 28, 2025. Modeled TPU-hour cost
SemiAnalysis, Datacenters 2027: The Year of Acceleration, Oct 19, 2026. ~50GW 2027 capacity forecast
SemiAnalysis, ClusterMAX 3.0, Sep 23, 2026. Operator ratings
Alex Song on GPU financing (X). Airline and aircraft-financing analogy
CoreWeave Q2 2026 results, Aug 11, 2026, and June 30 Form 10-Q. Income statement, cash flow, debt, leases, concentration, active power
CoreWeave pricing update, Sep 17, 2026; September investor presentation. Contract pricing, renewals, contracted power, project financing
CoreWeave DDTL 4.0 (Mar 31), August $2.6B facility, September $4.2B convertible. Project financing structure and terms
S&P Global Ratings, CoreWeave, April 2026. B+ issuer, B unsecured, recovery rating 5
NVIDIA Form 8-K, September 2025. $6.3B residual capacity agreement
BondTerminal, CoreWeave bonds, Oct 26-27, 2026. Indicative prices, yields, spreads
JunkBondInvestor, CoreWeave ($CRWV): $34 Billion of Equity and Bonds Yielding 15%...How? (Part 1), Oct 20, 2026. Parent funding gap framework